
TL;DR:
- Quantitative trading uses mathematical models and algorithms to generate buy and sell signals from market data. It involves a four-stage process: data collection, model development, signal generation, and order execution. Success depends on rigorous validation, realistic backtesting, and continuous monitoring of models and costs.
Quantitative trading is defined as the systematic use of mathematical and statistical models applied to market data to generate buy and sell signals, typically executed by computer algorithms. Known in professional circles as “quant trading,” this approach converts raw inputs like price and volume into systematic trading signals rather than relying on gut calls. Once reserved for hedge funds and institutional desks, quant trading is now accessible to individual traders through better data access, computing power, and platforms like TradingView. If you trade crypto, forex, or stocks and want a disciplined, repeatable edge, understanding how quant trading works is the right starting point.
What is quantitative trading and how does it work?
Quantitative trading works through a four-stage pipeline: data collection, model development, signal generation, and order execution. You feed historical and live market data into a mathematical model. The model outputs a signal. An algorithm acts on that signal.
One distinction matters here. Quant trading focuses on model building, meaning the research and signal generation side. Algorithmic trading focuses on execution, meaning the code that sends orders to a broker or exchange. In practice, the two work together, but they are separate workflows with separate risks.
Backtesting sits at the center of model validation. You run your model against historical data to see how it would have performed. The problem is that backtesting is vulnerable to serious distortions. Survivorship bias inflates hedge fund returns by an estimated 2–4% per year, because failed funds disappear from the dataset. Look-ahead bias is equally dangerous. It occurs when your model accidentally uses data that would not have been available at the time of the trade.
Pro Tip: Always build your backtest universe using point-in-time data. If your dataset excludes delisted stocks or failed funds, your results will look better than reality.
Quant strategies also vary widely by time horizon. High-frequency trading operates in milliseconds, capturing tiny price discrepancies thousands of times per day. Systematic macro strategies may hold positions for weeks or months. The model logic differs at each horizon, but the core process, data in, signal out, execute, remains the same.
What are the main quantitative trading strategies?
Quant strategies share one defining feature: systematic, measurable rules encoded in mathematical language that allow repeated testing and objective evaluation. Discretion plays no role once the model is live. That consistency is both the strength and the constraint of quant approaches.
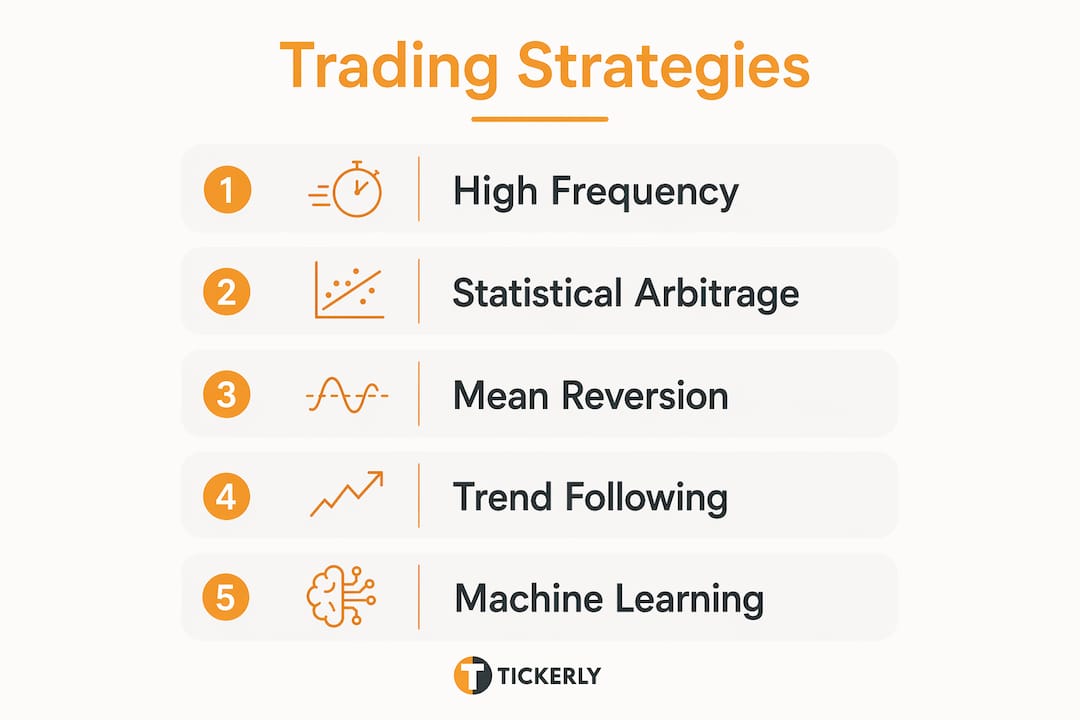
The most widely used strategies fall into three categories:
-
Statistical arbitrage. This strategy exploits temporary price divergences between related assets, such as two correlated stocks or a futures contract and its underlying index. The model identifies when the spread between two instruments moves beyond its historical norm and bets on reversion. It requires fast execution and tight cost control.
-
Trend following. Models detect sustained directional moves in price and ride them until momentum fades. Trend following works across asset classes, including commodities, currencies, and equities. It performs best during strong trending markets and struggles during choppy, sideways conditions.
-
Mean reversion. This approach assumes prices oscillate around a long-term average. When price moves too far above or below that average, the model takes the opposing position. Mean reversion strategies are common in equity pairs trading and fixed income.
-
High-frequency trading (HFT). HFT strategies execute thousands of trades per day, profiting from tiny bid-ask spreads and short-lived inefficiencies. They require co-location servers, ultra-low latency infrastructure, and direct market access. HFT is largely institutional territory.
Each strategy type suits different markets and time horizons. Quant trading covers both short intraday and longer systematic approaches, so your choice of strategy should match your execution infrastructure and risk tolerance.
What are the risks and challenges in quantitative trading?
Model overfitting is the most common failure mode in quant trading. Overfitting happens when a model is tuned so precisely to historical data that it captures noise rather than real market patterns. The model looks excellent in backtesting and fails immediately in live trading.
Backtesting biases compound this problem. The key risks include:
-
Survivorship bias. Your historical dataset only includes assets that still exist. Failed companies, delisted tokens, and closed funds are missing. Survivorship bias distorts mutual fund returns by roughly 0.9% per year and hedge fund returns by 2–4% per year.
-
Look-ahead bias. Your model uses information that was not available at the trade date. This is often accidental, caused by how data is structured in your research environment.
-
Transaction cost neglect. Ignoring slippage, commissions, and market impact is a critical error. Unmodeled transaction costs can nullify backtested profits entirely in live markets.
Market regime shifts create another layer of risk. A model trained on a low-volatility bull market will likely break down when volatility spikes or correlations change. Continuous monitoring and model maintenance are not optional. They are core workflow requirements.
Professional quant teams also use out-of-sample testing, walk-forward analysis, and stress testing against historical crisis periods. These techniques do not guarantee success, but they expose weaknesses before real capital is at risk. For a deeper look at validating trading strategies, rigorous backtesting methodology is the place to start.
How do technology and automation support quantitative trading?
Technology is not a supporting element in quant trading. It is the foundation. Without reliable data feeds, computing infrastructure, and execution software, no model can move from research to live trading.
A functional quant stack has four layers:
-
Data pipeline. Clean, point-in-time historical data and reliable live feeds are non-negotiable. Garbage data produces garbage signals, regardless of model quality.
-
Research and backtesting engine. This is where models are built, tested, and validated. Python with libraries like Pandas and NumPy is the standard for individual traders. Institutional desks often use proprietary systems.
-
Signal generation layer. The validated model runs in real time, processing incoming data and outputting trade signals on a defined schedule or trigger.
-
Execution layer. Signals are routed to a broker or exchange via API. Speed matters here. Latency between signal and execution can erode profitability, especially in faster strategies.
| Layer | Function | Key Risk |
|---|---|---|
| Data pipeline | Feeds clean market data to the model | Dirty or delayed data corrupts signals |
| Backtesting engine | Validates model on historical data | Survivorship and look-ahead bias |
| Signal generation | Produces buy/sell signals in real time | Model degradation over time |
| Execution layer | Routes orders to exchange via API | Slippage and latency |
Automation removes the two biggest sources of trading error: emotion and inconsistency. A model executes the same logic at 3:00 AM as it does at market open. It does not hesitate, second-guess, or deviate from its rules. Quant trading is increasingly accessible to individuals because platforms like TradingView now support Pine Script strategy development, and tools like Tickerly connect those strategies directly to live exchanges. The demand for quantitative expertise is also growing fast. Firms actively hire quantitative analysts to build and maintain these systems, which signals how central quant methods have become across the industry.
Understanding how data powers algorithmic strategies is the practical next step once you have a model concept in mind.
Key Takeaways
Quantitative trading succeeds when rigorous model validation, realistic cost assumptions, and continuous monitoring work together inside a disciplined execution framework.
| Point | Details |
|---|---|
| Core definition | Quant trading uses mathematical models to generate systematic buy and sell signals from market data. |
| Backtesting biases | Survivorship and look-ahead bias can materially inflate historical results and must be controlled. |
| Strategy variety | Statistical arbitrage, trend following, and mean reversion each suit different markets and time horizons. |
| Transaction costs | Unmodeled slippage and commissions can eliminate backtested profits in live trading. |
| Automation advantage | Separating signal generation from execution and automating order routing removes emotion and inconsistency. |
The part most traders skip until it’s too late
Most traders who explore quant methods focus almost entirely on strategy development. They spend weeks building a model, run a backtest that looks great, and go live. Then the model bleeds money for three months and they abandon it.
The real work is not building the model. It is stress-testing it honestly. I have seen traders with genuinely good signal logic lose money because they never accounted for bid-ask spread on illiquid assets, or because their backtest dataset quietly excluded every stock that went bankrupt during the test period. Those are not edge cases. They are the norm.
The other mistake I see constantly is treating a model as permanent. Markets change. A mean reversion strategy that worked beautifully in a low-volatility 2023 environment can fall apart when macro conditions shift. Monitoring model performance against out-of-sample benchmarks is not a one-time task. It is a weekly discipline.
My honest take: start with the simplest model that has a logical reason to work. Trend following on liquid assets is a better starting point than a complex multi-factor arbitrage strategy. Complexity adds parameters, and more parameters mean more ways to overfit. Once you have a simple model that survives realistic backtesting and a paper trading period, then you add sophistication. Not before.
The traders who succeed with quant methods long-term are not the ones with the most complex models. They are the ones who are most honest about what their backtest is actually telling them.— Jay
Tickerly and automated quantitative strategy execution
Quantitative trading strategies are only as good as their execution. A signal generated at the right moment loses its value if it takes seconds to reach the market.
Tickerly connects your TradingView strategies directly to live exchanges, converting Pine Script signals into executed trades with minimal latency. You build and validate your quant model in TradingView, set your alerts, and Tickerly handles the rest automatically, around the clock, without manual intervention. For traders running multiple strategies across crypto, forex, or stocks simultaneously, that consistency compounds over time. Explore automated bot efficiency to see how automation closes the gap between a validated quant model and consistent live execution. You can also browse TradingView strategy automation to get started with your first automated setup.
FAQ
What is quantitative trading in simple terms?
Quantitative trading uses mathematical models and computer algorithms to generate and execute buy and sell signals based on market data like price and volume, removing discretionary judgment from the process.
How is quantitative trading different from algorithmic trading?
Quantitative trading focuses on building and validating the signal-generating model, while algorithmic trading handles the execution of orders based on programmed rules. The two typically work together in a complete trading system.
Is quantitative trading profitable?
Quantitative trading can be profitable, but results depend heavily on model quality, realistic backtesting, and disciplined risk management. Backtesting biases like survivorship bias can make strategies appear far more profitable than they are in live markets.
Can beginners use quantitative trading strategies?
Quantitative trading for beginners is more accessible than ever due to platforms like TradingView and tools that connect strategies to exchanges via API. Starting with simple, well-understood strategies and rigorous backtesting is the recommended approach before committing real capital.
What software do quantitative traders use?
Quantitative traders commonly use Python with libraries like Pandas and NumPy for research and backtesting, TradingView with Pine Script for strategy development, and execution platforms that connect via API to brokers and exchanges.